Trinity Capital Deserves To Be A BDC Favorite (Archive)
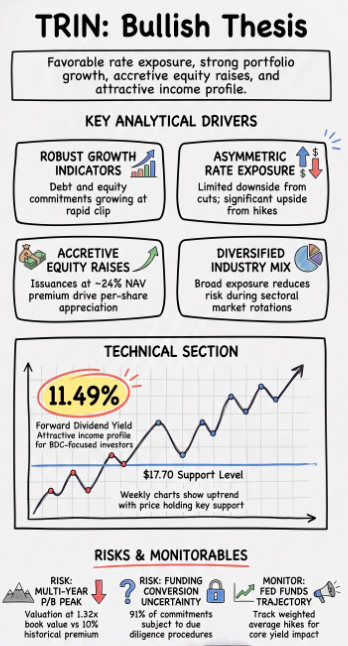
TRIN pairs strong funding momentum with rate upside and accretive NAV growth.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
- TRIN’s expanding debt and equity commitments support portfolio growth, although 91% of unfunded commitments remain subject to due diligence and investment-committee approval.
- Record Q2 fundings were back-end weighted, positioning Trinity Capital for a fuller contribution to net investment income in the upcoming Q3 quarter.
- TRIN has favorable interest-rate sensitivity, with materially greater earnings upside from higher rates than downside from moderate rate cuts.
- TRIN trades near a multi-year peak P/B valuation, but its 8.54x 1-yr fwd P/E remains modestly below the broader BDC peer median.
- Equity issuance above NAV has been accretive to per-share NAV, while the $17.70 area represents an important weekly-chart support level.
Read the full article here.