Sivers Semiconductors: Too Risky For Both Sells And Buys (Archive)
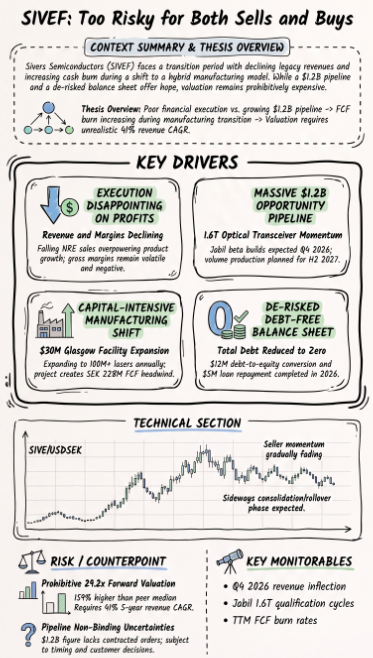
Sivers’ pipeline and balance sheet improved, but execution, cash burn, and valuation remain unresolved.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
- Sivers Semiconductors earns a Hold rating as revenue and margin execution remain weak despite a larger opportunity pipeline and a cleaner balance sheet.
- The $1.2B pipeline reflects non-binding potential revenue through 2030 and does not yet translate into contracted orders or near-term visibility.
- Free cash flow burn is set to worsen as Sivers invests around SEK 228M in its Glasgow indium phosphide manufacturing expansion over the coming year.
- Valuation is stretched at about 29x 1-yr FWD EV/revenues, and there is a 41% 5-yr revenue CAGR growth ask to justify the current price.
- Technical indicators show downside seller momentum fading, pointing more to sideways consolidation ahead.
Read the full article here.