LandBridge: I'd Love To Buy, But I Don't Like The Valuation (Archive, Full Access)
LandBridge’s water-royalty and data-center upside is compelling, but valuation is too rich.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
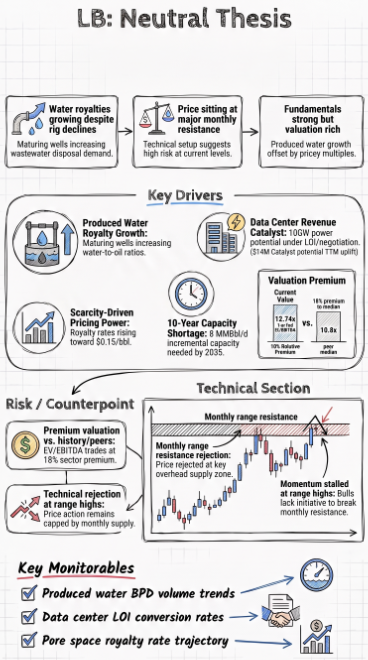
- LandBridge Company LLC's water royalty volumes are rising despite slower well drilling. This is due to increasing wastewater volumes from maturing Delaware Basin wells.
- A projected Delaware Basin disposal-capacity shortfall over the next 10 years should support higher royalty rates.
- LandBridge is pursuing data-center leases for up to 10 GW, creating meaningful long-term optionality that I estimate can lead to a 6% uplift on TTM revenues.
- LandBridge trades above its historical and peer 1-yr forward EV/EBITDA benchmarks, despite operating momentum and potential digital-infrastructure upside.
- LB stock has some bullish momentum but seems too risky to buy as it is at a monthly resistance level.
Read the full article here.