Credo: Yes, It Is Much Cheaper Now, But No, It Is Not Yet A Buy (Archive)
Credo is cheaper, but margin pressure, weak backlog, and concentration risk warrant patience.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
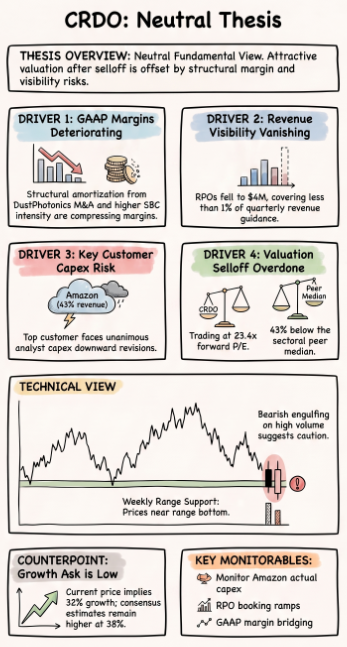
- Credo’s GAAP margins are compressing as DustPhotonics-related amortization and stock-based compensation widen the gap versus adjusted profitability.
RPOs have fallen to $4.2 million, leaving Credo increasingly reliant on continued quarterly bookings to sustain revenue growth.
Customer concentration heightens risk, especially if Amazon’s data-center capex expectations weaken and reduce demand for Credo's connectivity products.
CRDO’s 25% selloff has lowered its forward valuation materially, while consensus growth expectations remain above the earnings growth implied by its current multiple.
Bearish technical momentum remains strong, although CRDO is approaching the lower end of its weekly trading range.
Read the full article here.