Western Digital: Buy Aggressively Because The Market Is Wrong (Archive, Full Access)
The stock has been punished on news of capacity additions from a competitor, but this is an overreaction.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
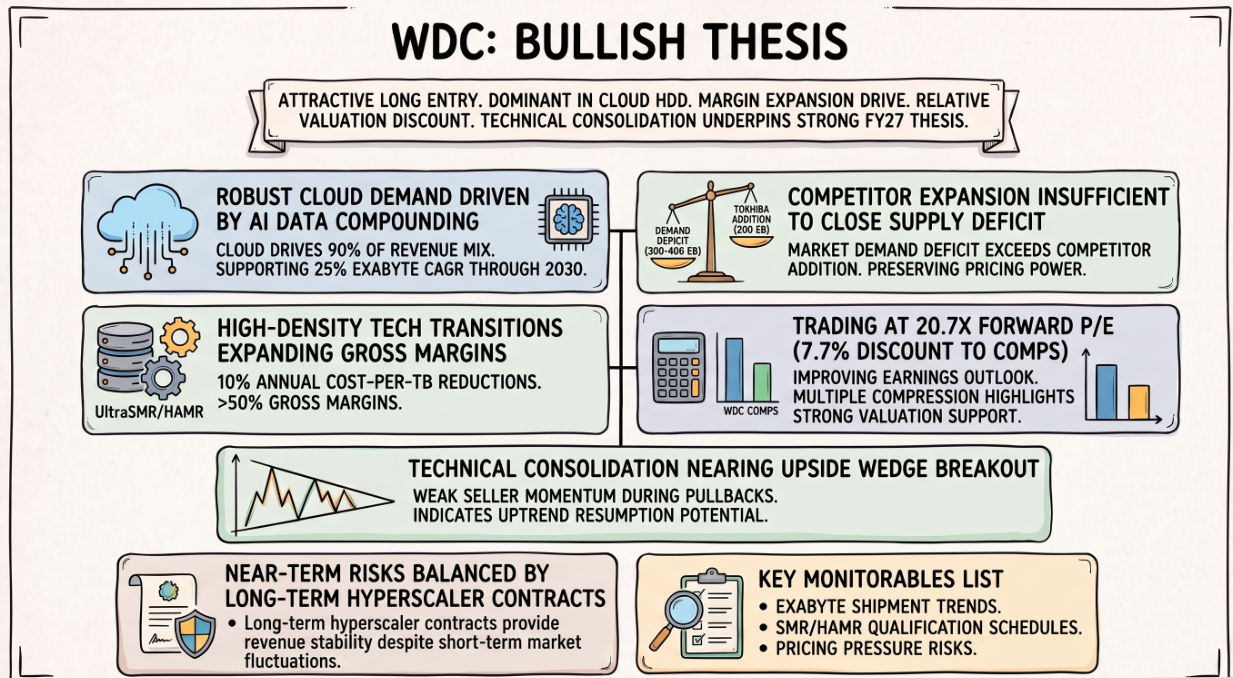
- Western Digital’s cloud business accounts for nearly 90% of revenue, with accumulating AI data supporting demand for high-capacity hard drives.
- Higher-capacity UltraSMR and HAMR drives could expand margins, with management targeting roughly 10% annual cost-per-terabyte reductions over the medium to long term.
- Toshiba’s planned expansion raises pricing risks, but Western Digital’s higher-capacity products and long-term customer agreements provide competitive protection.
- WDC trades at a 7.7% discount to comps on a 1-yr FWD P/E basis, despite improving earnings expectations.
- Western Digital’s share price is consolidating within a wedge after a prolonged uptrend. I expect the stock to break upward.
Read the full article here.