Seagate: Buy When The Market Panics (Archive, Full Access)
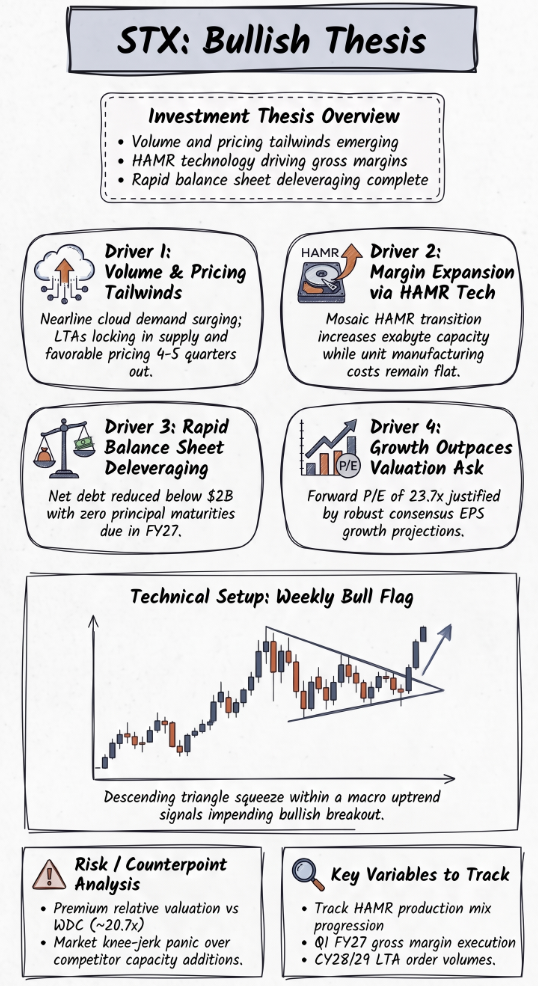
Volume and pricing tailwinds, a favorable mix shift toward higher-margin products, and a deleveraged balance sheet.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
- Seagate benefits from rising data center storage demand and stronger HDD pricing, with longer customer commitments supporting visibility and AI inference expanding storage needs.
- Higher-capacity HAMR drives have lower manufacturing costs per terabyte, while stronger pricing and a favorable product mix could push gross margins above 65% within 2 years.
- Seagate’s rapid deleveraging strengthens its balance sheet and reduces exposure to elevated interest rates.
- Seagate trades at a 23.7x 1-year forward P/E, which is above its peers. But projected earnings growth exceeds the ~35% 5-year earnings CAGR needed to justify its valuation.
- Seagate’s weekly chart shows a potential bull flag, with limited selling pressure and intact support suggesting the longer-term uptrend could resume.
Read the full article here.