AppLovin: I Was Wrong, This Is A Sell (Archive)
There is persisting weakness in ads' performance and concerns about more intense competition.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
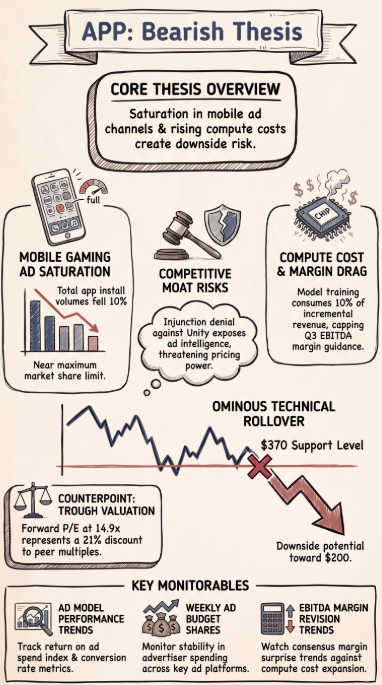
- AppLovin's mobile-gaming advertising growth faces saturation risk as app-install volumes decline, while model-performance improvements have recently slowed.
- The Unity dispute highlights competitive risks around advertising data and auction intelligence, although AppLovin's weekly ad budget share has remained resilient.
- Higher spending on model training and inference may pressure adjusted EBITDA margins as AppLovin spends on more complex advertising models.
- APP trades near trough 1-yr fwd PE levels and at a large relative discount to peers. The undemanding valuations are a source of upside risk.
- APP's monthly chart shows lower highs and lower lows after breaking below approximately $370, with the next major support area near $200.
Read the full article here.