Sandisk: It's The Perfect Time To Load Up (Archive, Full Access)
Long-term contracts, capital efficiency, and HBF upside support a Strong Buy on SNDK.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
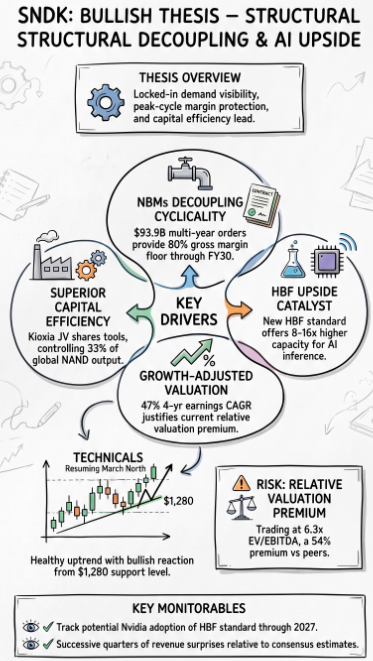
- Sandisk’s 8 multiyear deals with datacenter players provide substantial revenue visibility, covering 50% of FY27 and 67% of FY28 bit shipments.
- Sandisk’s Kioxia joint venture lowers capital intensity through shared technology development, manufacturing tools, and NAND production capacity through 2034.
- High-bandwidth flash (HBF) could address AI inference memory-capacity constraints, with 2027 product launch plans creating upside beyond Sandisk’s current long-term financial outlook.
- Sandisk trades above memory peers on a 1-yr fwd EV/EBITDA basis, but high earnings growth projections, supported by long-term contract visibility, make the stock look cheap.
- SNDK's correction seems to be over as the bulls are defending grounds and pushing up from a key technical support level amid a broader, healthy uptrend.
Read the full article here.