Meta: Muse Is Nice, But Not Enough (Archive)
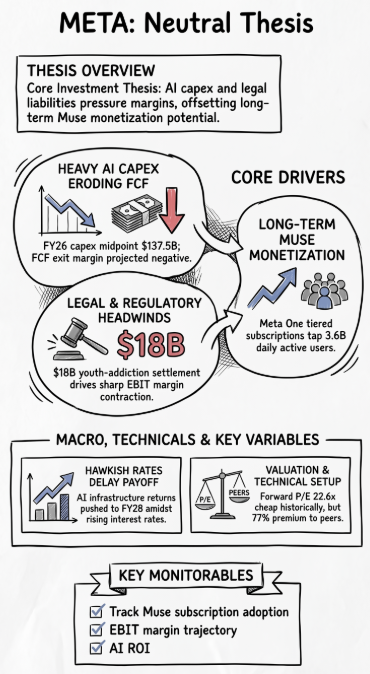
Muse and Meta One adoption vs the long duration of growth bets that carry both monetization visibility risks and opportunity cost risks with rising rates.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
- Meta Platforms, Inc.’s $137.5 billion AI capex midpoint could push FY26 FCF negative, raising risk over returns from data-center investments built ahead of visible demand.
- Significant legal and regulatory headwinds, including an $18B settlement and ongoing $35–40B claims, are materially impacting margins and may hit ads impressions later on.
- Muse and Meta One subscriptions could diversify a business that still derives nearly 98% of revenue from advertising. This would be the main stock driver going forward.
- Meta trades below its historical 1-yr fwd P/E but at a substantial premium to social-media peers.
- The monthly technical charts show an uptrend constrained by a broad trading range.
Read the full article here.