Infleqtion: Still Promising With Diversifying Revenue Streams, But Not As Clear A Buy (Archive)
The revenue progress is good but the valuations aren't compelling.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
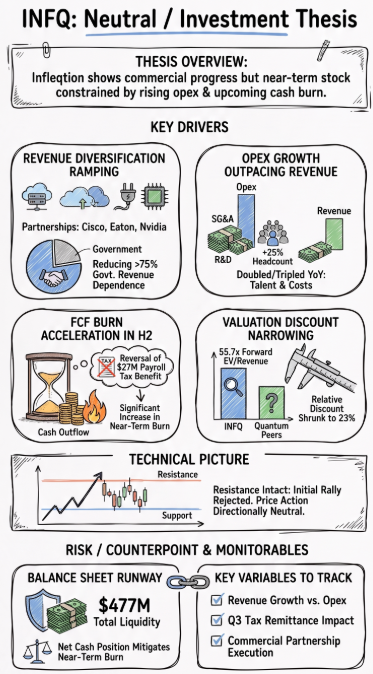
- Infleqtion is diversifying revenue streams through commercial partnerships, but government contracts still account for over 75% of revenues.
- OPEX growth is outpacing revenue growth, with SG&A and R&D more than doubling YoY, though INFQ maintains a strong $477M liquidity position.
- Cash flow is set to worsen in the near term, with capex expected to ramp up in H2 FY26 and a modest uptick in cash burn for FY26.
- Valuation is probably near fair value, although the size of the discount vs. quantum peers has shrunk.
- The technical charts show range-bound action, making a clear bullish bias harder to justify.
Read the full article here.