CoreWeave: Don't Be Tempted By The Impressive Growth (Archive)
The revenue outlook is strong but the leverage and funding risks keep me away.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
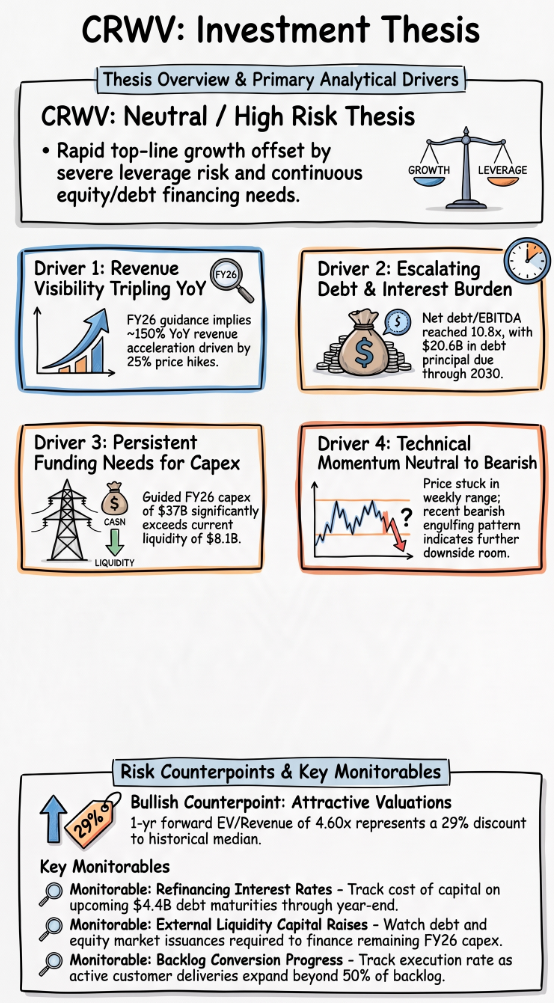
- CoreWeave’s expanding backlog, sold-out near-term capacity, higher prices, and upward revenue revisions point to exceptionally strong FY2026 revenue growth.
- High leverage, negative free cash flow, and substantial debt maturities increase refinancing risk, particularly given a hawkish rates rates environment.
- CoreWeave’s $37B annual capex plan exceeds current liquidity, making further debt, equity issuance, or other external financing necessary.
- CRWV trades below its historical and peer 1-yr fwd EV/revenue multiples despite rising consensus revenue estimates, indicating an attractive valuation overall.
- CRWV remains range-bound, with bearish near-term price momentum leaving room for a decline toward technical support.
Read the full article here.