Calumet Has Powerful Favorable Macro And Industry Catalysts (Archive)
Calumet enjoys volume growth for higher priced products and favorable industry and energy macro conditions.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
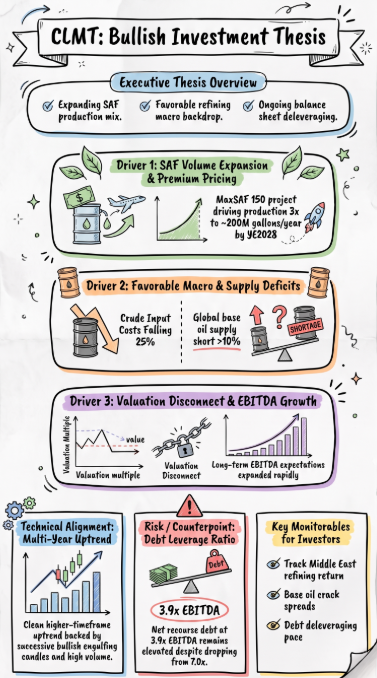
- Calumet is expanding SAF production from more than 60M gallons annually to around 200M gallons by the end of 2028, improving product mix and pricing realization.
- Premium SAF pricing, tight base-oil supply, and elevated diesel crack spreads support Calumet’s specialty-products and Montana Renewables earnings outlook.
- Montana Renewables expects $50M of incremental adjusted EBITDA in H2 FY26 by extending conventional refining operations before further SAF conversion.
- Net recourse debt to adjusted EBITDA declined to 3.9x from 7.0x a year earlier. But I say leverage remains a risk to closely monitor.
- CLMT’s forward EV/EBITDA multiple has corrected sharply, while forward EBITDA expectations have improved. The stock's valuation premium vs. peers is smaller than usual.
Read the full article here.