Broadcom: 5 Reasons To Buy This Dip (Archive, Full Access)
Broadcom wins from custom AI chip trends, margin expansion and high FCF margins that can easily fund capex expansions.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
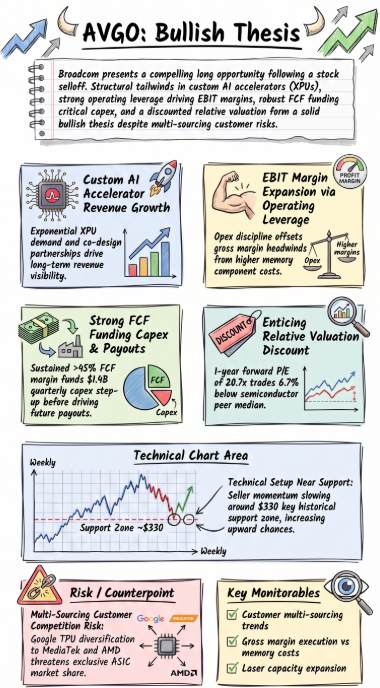
- Broadcom’s custom AI accelerators and networking silicon are driving rapid growth, supported by co-design relationships with 6 frontier-model developers.
- Google’s supplier diversification and rising custom-chip competition could pressure Broadcom’s share of future TPU design work.
- The custom chip product mix is pressuring gross margins due to higher memory content, which is getting more expensive. But operating leverage is sustaining EBIT margin expansion regardless.
- FCF margins above 45% support major substrate and laser-capacity investments while preserving scope for higher shareholder payouts later.
- AVGO trades below its semiconductor peer median 1-yr fwd P/E despite accelerating AI revenue and improving earnings expectations.
Read the full article here.