Alphabet: Buy Before It Cashes In On Its TPUs (Archive)
Strong growth and margin tailwinds in Google Cloud and TPUs offsets the hiccups from European regulations on Search revenues.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
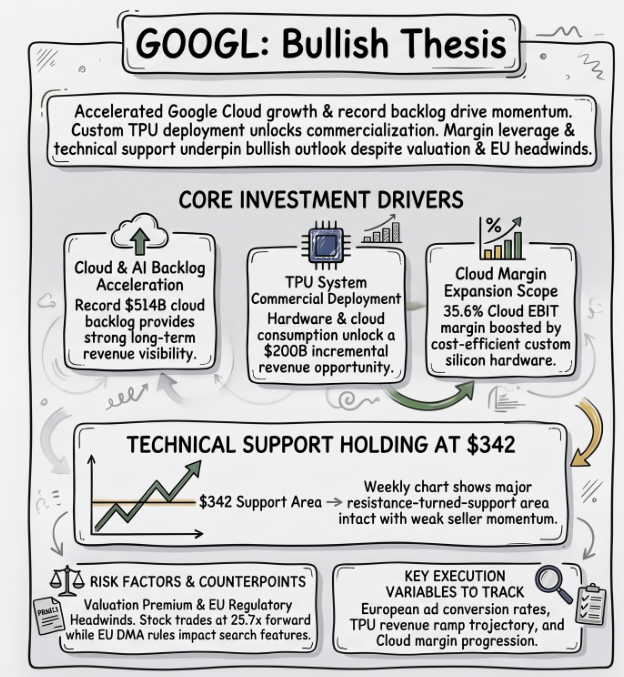
- Google Cloud's accelerating growth, Gemini adoption, and $514B backlog provide substantial AI-driven revenue visibility for Alphabet, with more than half of the backlog expected to convert within 24 months.
- Commercial TPU deployments could create a major incremental revenue stream from 2027, while improving Alphabet's revenue return on AI infrastructure spending.
- EU Digital Markets Act remedies may weaken European Search engagement and ad conversion, while fines and follow-on litigations are other risks to watch.
- Google Cloud's 35.6% EBIT margins and incremental YoY EBIT margins above 50% indicate scope for further operating leverage as AI infrastructure and software adoption scale.
- GOOGL trades above its long-term and peers' 1-yr fwd PE benchmarks, creating some elevated valuation risk. But the technical charts are supportive of a bullish stance.
Read the full article here.