Aeluma: The Numbers Don't Match The Narrative (Archive)
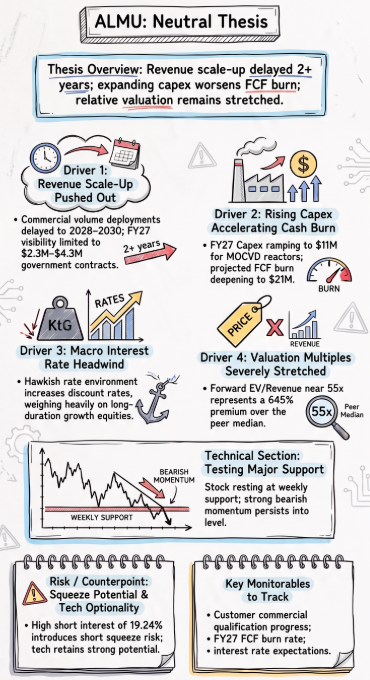
Promising technology and high potential is there but also a prolonged revenue scale-up in a hawkish rate environment amid rising costs and worse FCF burn.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
- Aeluma’s revenue scale-up remains at least 2 years away, with volume deployments expected in 2028–2030 and customer qualification requirements slowing commercialization.
- Rising operating costs and $11M in planned FY27 capital spending could drive approximately $21M in FCF burn.
- Expectations for higher interest rates create a headwind for Aeluma, given its lengthy commercialization timeline and distant profitability.
- ALMU’s 19.24% short interest creates short-squeeze potential, adding upside risk despite weakening fundamentals.
- Aeluma trades near 55x 1-yr fwd EV/Revenue, above its historical median and peer valuations, even as revenue expectations decline.
Read the full article here.