Adamas Trust: Why I Prefer The Preferred Shares To The Common Stock (Archive)
Neutral as rising rates are a headwind, but expanding business purpose loan originations are good as are the fixed-to-floating preferred stock conversions.

This 5-Minute Pitch was originally published on Seeking Alpha. It is shared here to showcase my work and track record. I also publish full 5-Minute Pitches on this site. This will be behind a paywall, accessible to Hunter Tier members.
Elevator Pitch
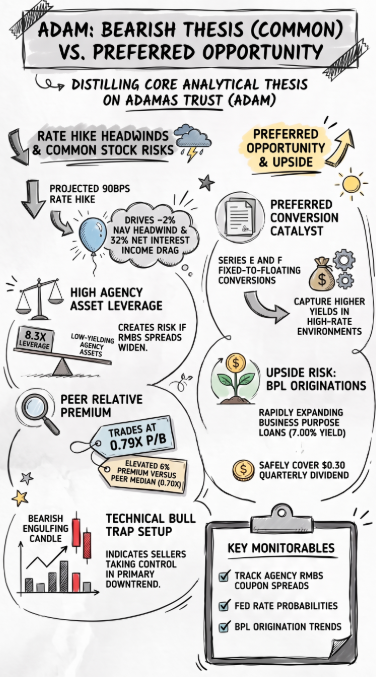
- Rising rates could reduce Adamas Trust’s net interest income and book value, while its leveraged agency mortgage portfolio adds exposure if spreads widen.
- Growing business-purpose rental loans offer an offset, with a 7.00% average coupon on the held portfolio and improving earnings available for distribution.
- Adamas Trust, Inc. trades below its historical P/B multiple, but its valuation relative to mortgage REIT peers is less compelling.
- The stock’s longer-term downtrend and recent high-volume decline raise the possibility that its recovery is a bull trap.
- The Series F preferred shares are scheduled to begin floating in October 2026, joining Series E in offering coupons linked to short-term rates. This is good in a rising-rate environment.
Read the full article here.